Section 36 AJA 1970: Delay Mortgage Repossession
Behind on your mortgage and facing a court date? Learn how the court can give you more time, what evidence persuades a judge and why bridging loans are treated differently.
 LEXLAW Solicitors & Barristers
Behind on your mortgage and facing a court date? Learn how the court can give you more time, what evidence persuades a judge and why bridging loans are treated differently.
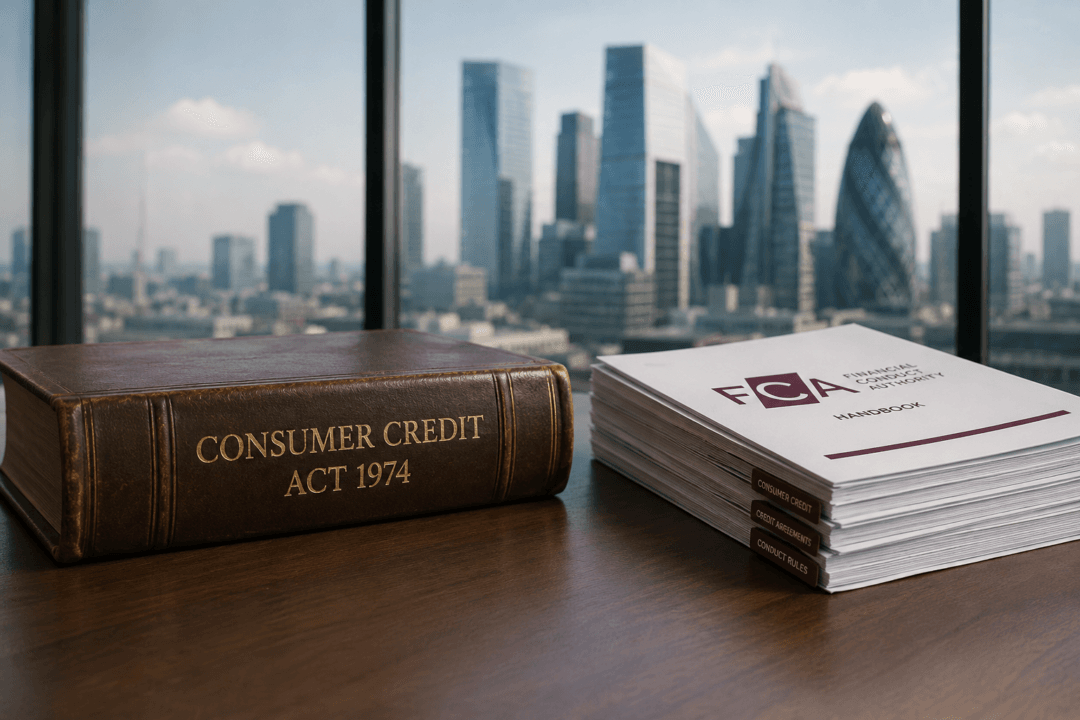
From outdated statute to FCA rulebook: the Consumer Credit Act 1974 is facing its most significant overhaul in fifty years. Automatic sanctions that have protected borrowers for decades are proposed for repeal, voluntary termination rights hang in the balance, and the window to enforce existing statutory protections is closing. Here is what every borrower needs to know before the law changes.
Growing scrutiny of regulatory oversight has reignited claims that small businesses were exposed to hidden liabilities through complex lending structures, raising significant legal questions around misrepresentation, regulatory accountability, and SME redress.
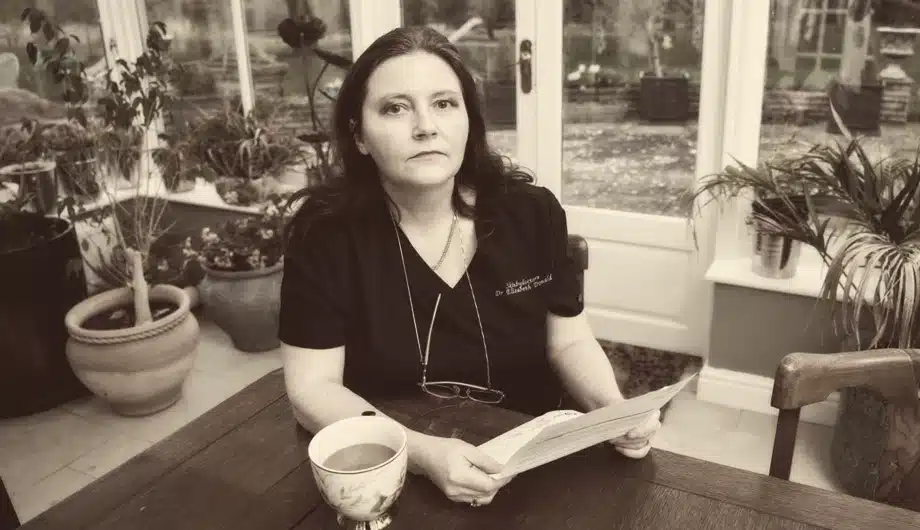
Our client, Dr Elizabeth Donald represented by Jaron Dosanjh, told The Times that MFS’s collapse had been a “nightmare” in regards to her personal portfolio. Barclays, Santander and Wells Fargo are some of the institutions thought to be caught up in the Mayfair lender’s collapse — but what about individuals? Article by James Hurley, Assistant Business Editor, The Times

In Manolete Partners Plc v Trevor Howarth [2024] EWHC 2294 (Ch), the High Court dismissed a £101,000 claim against the former CEO of One Legal Services. Manolete alleged that repayments to Mr Howarth’s director loan account during the firm’s CVA were unlawful preferences under the Insolvency Act 1986. Judge Barber disagreed, holding the payments were made in good faith.

McGuinness v Goldentree [2025] EWHC 870 (Ch) clarifies investment property loan exemptions under Article 61A FSMA 2000. The High Court struck out regulatory challenges to commercial development finance, confirming contemporaneous evidence establishes business purposes. The judgment reinforces that former directors lack litigation authority during administration without administrator consent. This decision protects legitimate commercial lending from spurious consumer credit challenges whilst emphasising robust documentation practices for development finance practitioners.
In this case our lawyers defeated “London Credit”; a bridging lender that demanded circa £160,000.00 GBP. We applied to the High Court and successfully set aside a default judgment then forced the withdrawal of a statutory demand, and 3 interim charging orders. We then forced the other side to settle – for a fraction of the sum demanded.